The UAE’s e-invoicing rollout brings important deadlines and potential administrative penalties for businesses that fail to meet their obligations. Understanding the applicable timelines, penalty rules, and implementation requirements can help businesses prepare for the transition.
Published: 29 October 2026 | Category: Tax Updates & Compliance
Understanding the AED 5,000 Penalty
Businesses across the UAE are preparing for the introduction of mandatory electronic invoicing, with an important deadline approaching for companies in the first implementation phase.
The Federal Tax Authority (FTA) has urged businesses subject to the e-invoicing framework to comply with the prescribed timelines and avoid administrative penalties.
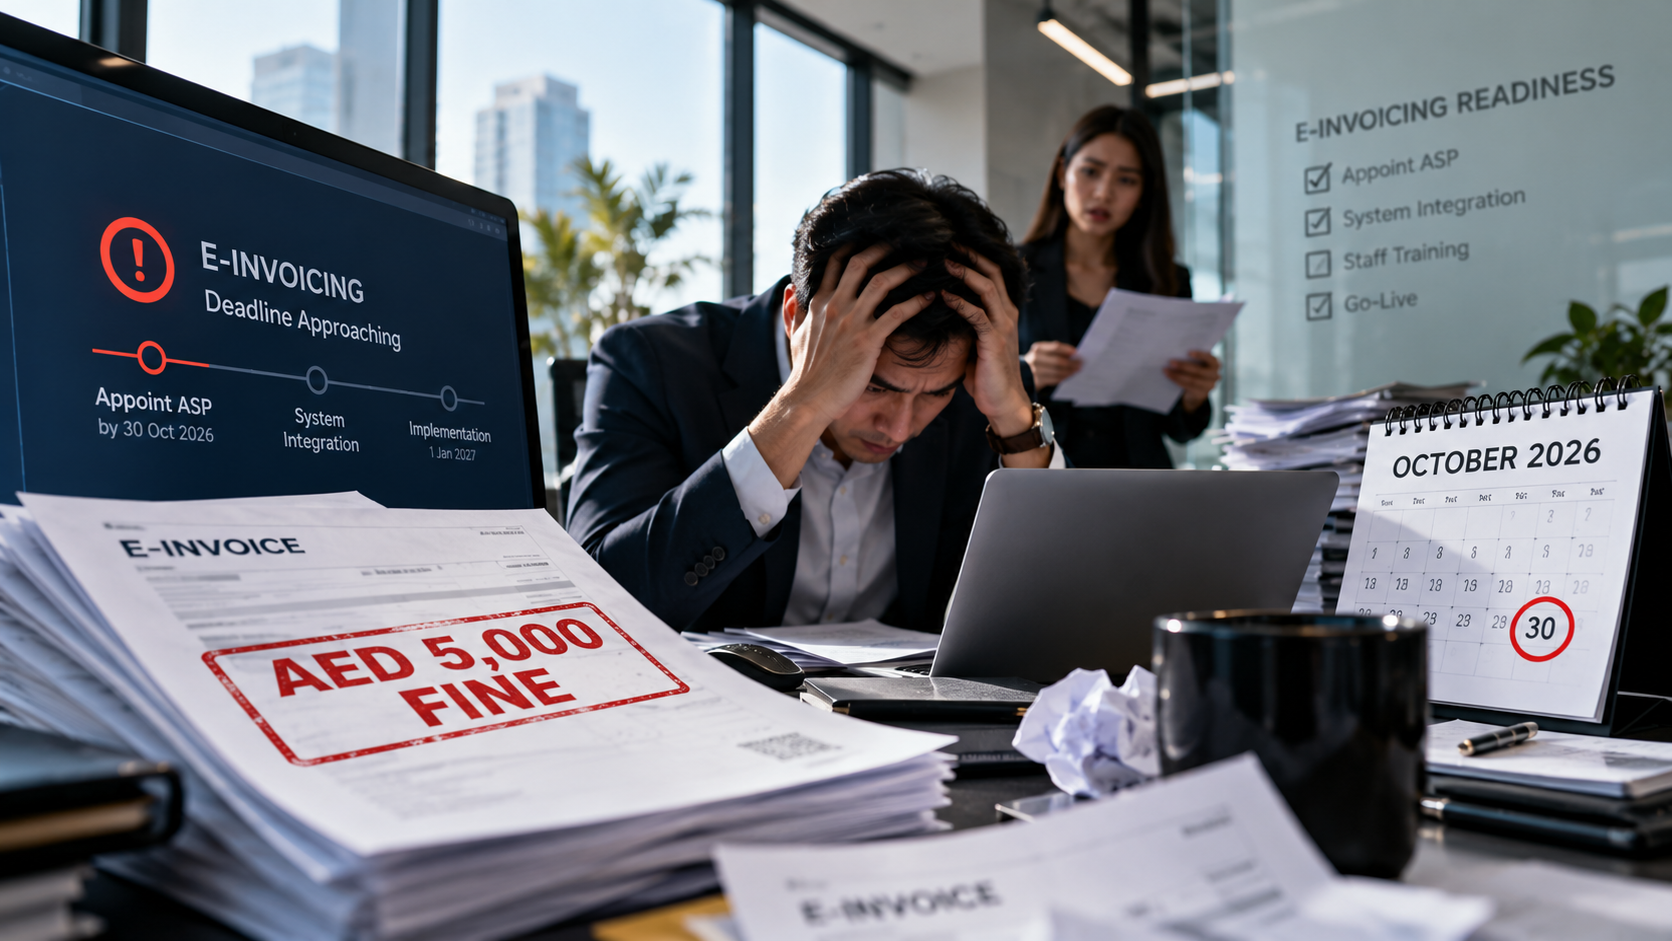
For businesses with annual revenue of AED 50 million or more, 30 October 2026 is the deadline to appoint an Accredited Service Provider (ASP). These businesses are subsequently required to implement the electronic invoicing system by 1 January 2027.
Under Cabinet Decision No. 106 of 2025, failure to implement the electronic invoicing system within the prescribed timeline, including failure to appoint an ASP on time, can result in an administrative penalty of AED 5,000 for each month or part of a month of delay.
This is not a AED 5,000 daily penalty for the relevant implementation or ASP appointment violation. The applicable penalty depends on the nature of the breach and the relevant provisions of the legislation.
Other violations carry separate penalties. For example, failure to issue and transmit an electronic invoice within the required timeframe may result in a penalty of AED 100 per invoice, subject to a maximum of AED 5,000 per calendar month.
Businesses should distinguish between penalties for missed implementation deadlines and those relating to individual invoicing violations.
UAE E-Invoicing Deadlines
The UAE is introducing electronic invoicing through a phased implementation process. The standard deadlines vary according to the applicable business category and annual revenue.
The published timeline includes:
- Businesses with annual revenue of AED 50 million or more: Appoint an ASP by 30 October 2026 and implement the system by 1 January 2027.
- Businesses with annual revenue below AED 50 million: Appoint an ASP by 31 March 2027 and implement the system by 1 July 2027.
Businesses should confirm their applicable category and review the relevant legislation and official guidance, particularly where specific circumstances may affect their obligations.
What Does E-Invoicing Implementation Involve?
Electronic invoicing involves more than issuing invoices in a digital format. It requires invoices to be created and exchanged in a structured format that compatible systems can process.
For businesses preparing for implementation, this may involve reviewing accounting software, assessing system integration requirements, checking customer and supplier information, and updating internal invoicing procedures.
The transition may also require coordination between finance, accounting, tax, and IT teams to ensure that the new processes operate effectively.
Key Considerations for Businesses
Businesses preparing for e-invoicing should consider several areas.
Accounting Systems and Integration
Existing accounting or enterprise resource planning (ERP) systems should be assessed to determine the changes required to support electronic invoicing.
Data Accuracy
Customer, supplier, and tax information should be reviewed to identify inconsistencies that could affect invoice processing.
Internal Procedures
Businesses should review how invoices are prepared, approved, issued, corrected, and recorded, and determine how these processes will operate under the new system.
Testing and Readiness
Coordination with the selected ASP can help establish technical requirements, integration plans, and testing activities before the implementation deadline.
Employee Awareness
Employees responsible for invoicing and financial records should understand the updated procedures and their responsibilities.
The specific technical and regulatory requirements should be confirmed according to each business’s circumstances.
What Happens Next?
For businesses subject to the first implementation phase, appointing an ASP by the prescribed deadline is an immediate priority. The subsequent period should be used to prepare systems and processes for implementation by 1 January 2027.
Businesses covered by later phases have additional time under the standard timeline, but should also review their systems and requirements well in advance.
Where the applicable deadline or regulatory obligation is unclear, businesses should consult the FTA’s official guidance or seek advice from a qualified tax professional.
Conclusion
The introduction of mandatory electronic invoicing represents a significant change in how businesses prepare and exchange invoices in the UAE.
Understanding the implementation timeline, distinguishing between applicable administrative penalties, and assessing operational readiness can help businesses approach the transition with greater clarity.
Businesses should rely on official guidance and the relevant legislation when determining their obligations and should not assume that the same deadline or penalty applies to every situation.
Disclaimer: This article is for general informational purposes only and does not constitute tax or legal advice. Refer to the applicable UAE legislation and the latest official guidance for the complete requirements.

